Selling a business often turns years of work and business equity into a significant pool of capital. That changes the financial questions. Instead of asking how to grow and operate the company, you may be asking: how much can we spend, how should we hold and invest the proceeds, and what happens to the wealth over the next 20 or 30 years?
Those questions rarely sit neatly with one professional. The accountant may be focused on the sale structure and capital gains tax (CGT), your solicitor on agreements and estate documents, and your financial adviser on investment, superannuation and sustainable income. The decisions need to work together.
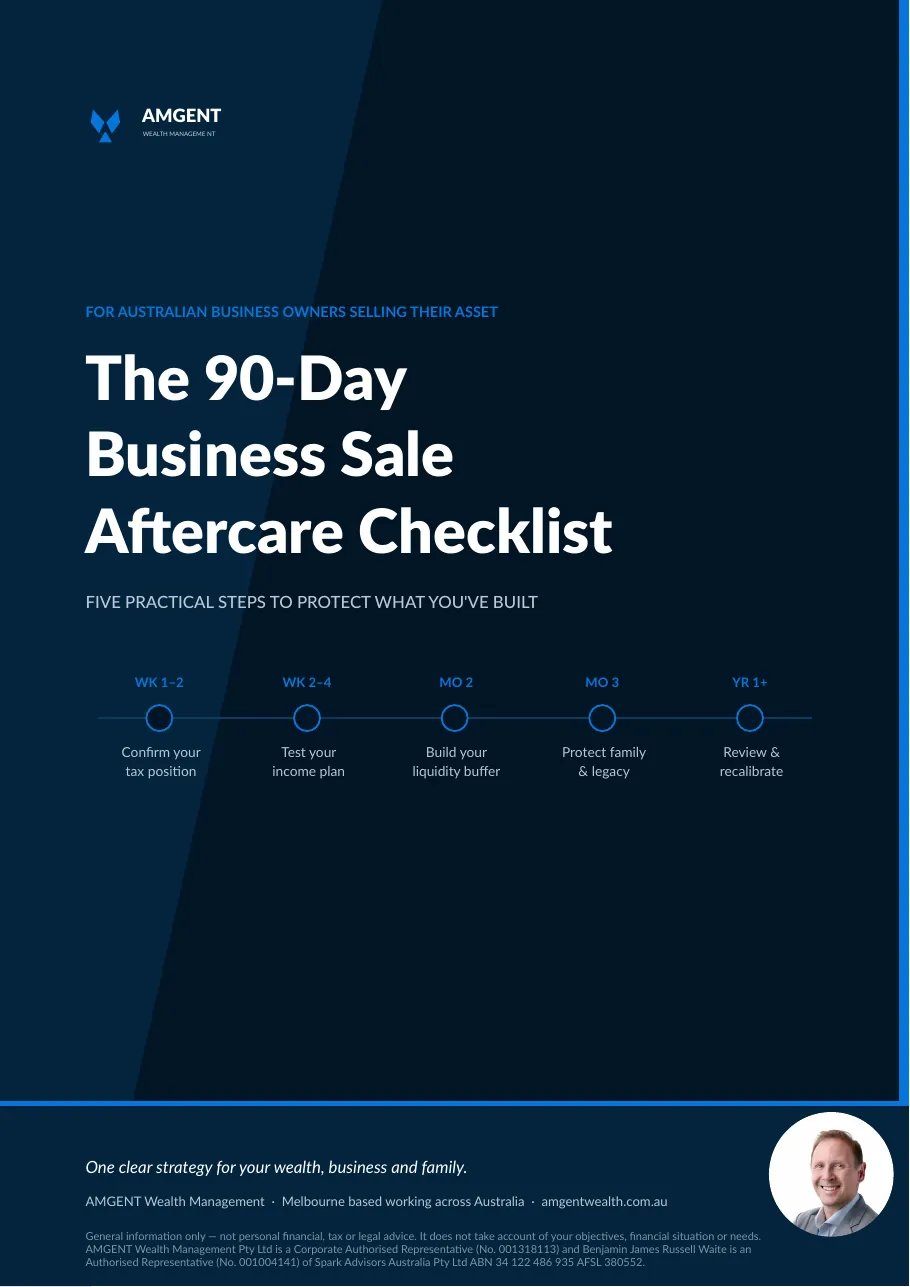
This guide follows the five-step framework in AMGENT's 90-Day Business Sale Aftercare Checklist. The timetable is a planning prompt—not a statement that every tax decision can wait until after settlement. Some issues should ideally be resolved before a contract is signed.
1. Weeks 1–2: confirm your business sale tax position
Your first priority is clarity about the money you actually have. The amount shown on the sale agreement is not necessarily the amount available to invest or spend after tax, debt repayments, transaction costs and any retained obligations.
Review the sale structure and capital gains treatment with your accountant. Australia has four small business CGT concessions that may apply when their specific requirements are met: the 15-year exemption, 50% active asset reduction, retirement exemption and small business rollover. They do not apply automatically to every business sale.
Eligibility and the order of applying relevant concessions can matter. Tests can involve the type of assets sold, ownership history, aggregated turnover, net assets, the active asset rules and the involvement of connected entities. The Australian Taxation Office's small business CGT concessions guidance is a starting point; your accountant should determine how it applies to the transaction.
- What is the confirmed or estimated after-tax amount from the sale?
- Which CGT concessions, if any, are available, and on what basis?
- Are there contribution opportunities or deadlines relating to superannuation?
- Which documents and valuations should we retain for ATO and future planning purposes?
There can be opportunities to contribute eligible amounts to super, including rules specifically relating to qualifying small business CGT proceeds. Ordinary contribution caps and special CGT-related arrangements are not interchangeable, and documentation and deadlines matter. Review these with your advisers before moving money.
Outcome for this step: a clear statement of net proceeds, tax obligations, relevant deadlines and the amount available for the next part of the plan.
2. Weeks 2–4: test how much income the proceeds can support
For some owners, a sale coincides with retirement. Others plan to work part-time, begin another venture or support family members. Either way, the business may no longer provide regular cash flow, so the capital needs a different job.
Start with your household's annual spending: essentials, lifestyle goals, periodic major purchases, any debt repayments and allowances for unexpected costs. Then list other income sources such as rental income, dividends or superannuation pensions. Consider whether Age Pension eligibility might become relevant later, without assuming you will qualify.
The important test is not simply whether a lump sum looks large. It is whether your assets, income and planned spending can remain workable through market falls, inflation and a long retirement.
Why investment returns early in retirement matter
When a portfolio is funding withdrawals, a downturn early in the process can be particularly difficult. Taking money out while asset prices are low means fewer assets remain invested for a possible recovery. This is often called sequence-of-returns risk.
Rather than relying on a fixed withdrawal percentage, ask your adviser to model a range of market and spending outcomes. A useful plan distinguishes spending you must cover from spending you could reduce if circumstances changed.
- Available sale proceeds after allowing for liabilities and tax
- Essential and discretionary annual household expenses
- Superannuation balances, investments, cash and other income
- Retirement timing, dependants and major one-off commitments
Outcome for this step: a spending and income plan based on your circumstances, including what would happen if markets perform poorly early on.
3. Month 2: build a liquidity buffer before investing the rest
Business owners may be familiar with cash being tied up in the company. Following a sale, accessible cash is valuable for a different reason: it can help fund living expenses and unexpected costs without forcing investment sales at a difficult time.
AMGENT's checklist suggests calculating several years of essential spending and considering a multi-year reserve in relatively stable assets, such as cash or term deposits. The right amount is personal: holding more cash can reduce forced-sale risk but may also limit long-term growth and expose purchasing power to inflation.
Discuss how your cash reserve, defensive investments and longer-term growth assets would work together. Agree how withdrawals would be funded if markets fall, when the plan would be reviewed, and what would trigger changes. Avoid rules that depend on an assumed return or guarantee that investments can never fall.
This is also the time to stage significant purchases. A property purchase, family gift or lifestyle upgrade may be entirely appropriate—but it should sit inside a plan that accounts for future income and liquidity needs.
- What do we realistically need to spend over the next 12 months?
- How much should remain accessible for emergencies and planned expenses?
- How would we fund withdrawals if investment markets fell?
- How and when would we replenish the buffer?
4. Month 3: update estate planning, super nominations and family intentions
A sale can substantially change how much of your wealth is held personally, through trusts or companies, or within superannuation. Documents prepared years earlier may no longer reflect your current arrangements or wishes.
With your solicitor and relevant advisers, review wills, enduring powers of attorney and the way assets are owned. Check superannuation death benefit nominations, particularly if you have an SMSF. Super benefits are generally dealt with under superannuation law and fund rules and do not necessarily follow the terms of your will.
Where it is relevant, discuss the needs of a spouse or partner, children, blended family members and other intended beneficiaries. Clear documentation and family conversations can reduce confusion, although they cannot guarantee that disputes will never arise.
Outcome for this step: an up-to-date list of estate planning instructions, documents and actions for the appropriate legal professionals.
5. Year 1 and beyond: review the plan rather than setting and forgetting it
The strategy that fits immediately after a sale may not fit five years later. Markets move, super and tax rules change, family circumstances evolve and spending habits become clearer once work has stopped.
Choose an annual review date and ask your financial adviser to compare your plan with your actual experience. Review withdrawals and income sources, investment risk, cash reserves and any relevant tax or superannuation changes. Significant life events may justify an earlier review.
The goal is not to react to every market headline. It is to make considered adjustments when the facts about your family, assets or financial position have materially changed.
90-day business sale aftercare timeline
| When | Priority | What to organise |
|---|---|---|
| Weeks 1–2 | Tax position | CGT treatment, super contribution eligibility, records and deadlines |
| Weeks 2–4 | Retirement income | Net proceeds, planned spending, other income and stress testing |
| Month 2 | Liquidity | Accessible cash, defensive assets and withdrawal approach |
| Month 3 | Family and legacy | Will, power of attorney, beneficiaries and asset ownership |
| Each year | Review | Spending, tax settings, risk, estate plan and major changes |
Timing note: this is a suggested review sequence, not a legal or tax deadline calendar. Your specific transaction may require action sooner—including before completion.
Free download: The 90-Day Business Sale Aftercare Checklist
Want to put these steps into practice? AMGENT's seven-page PDF breaks the plan into checkable actions for business owners and includes the information to discuss with your accountant, solicitor and financial adviser.
 7-page PDF · Free resource
Get your 90-day aftercare checklist
Enter your name and email. After AMGENT receives your request, your PDF download will start automatically.
When is a financial adviser useful after a business sale?
If decisions about superannuation, investing, retirement income and family wealth are connected, a joined-up strategy may be more useful than treating each decision in isolation. An accountant should advise on the business sale's tax consequences, while a solicitor should advise on legal documents. A financial adviser can help you evaluate how the available proceeds may support your goals and coordinate those decisions within their authorised advice scope.
AMGENT Wealth Management is Melbourne based and works with clients across Australia. To explore your own situation, read about financial planning for business owners, or use the pre-sale business exit checklist if you have not yet settled the sale.
Your business sale deserves more than a one-off investment decision.
Discuss what the proceeds need to achieve, how your plan connects with tax and legal advice, and which decisions matter first.
Frequently asked questions
What should I do immediately after selling my business in Australia?
Confirm your tax and settlement documents with your accountant, calculate how much money is actually available after liabilities and tax, and arrange a joined-up financial plan before making large commitments.
Do I have to pay capital gains tax when I sell my Australian business?
A business sale may trigger CGT, but eligibility for small business concessions depends on the ownership, asset, business and transaction circumstances. Ask your accountant to confirm the treatment and deadlines.
Can I put business sale proceeds into superannuation?
Depending on your circumstances, contribution limits and potentially special CGT-related contribution rules may affect what can be contributed. Confirm your eligibility, paperwork and timing with qualified advisers before transferring money.
How should I invest money after selling a business?
Begin with near-term spending needs, the tax position, access to cash and the level of investment risk you can afford. A suitable investment mix depends on your objectives and personal situation; there is no one-size-fits-all allocation.
Should I speak to a financial adviser before or after selling my business?
Planning before settlement can preserve more options, especially where tax, super and structures are concerned. If the sale has already settled, seek coordinated accountant, legal and financial advice promptly rather than rushing into investments.